
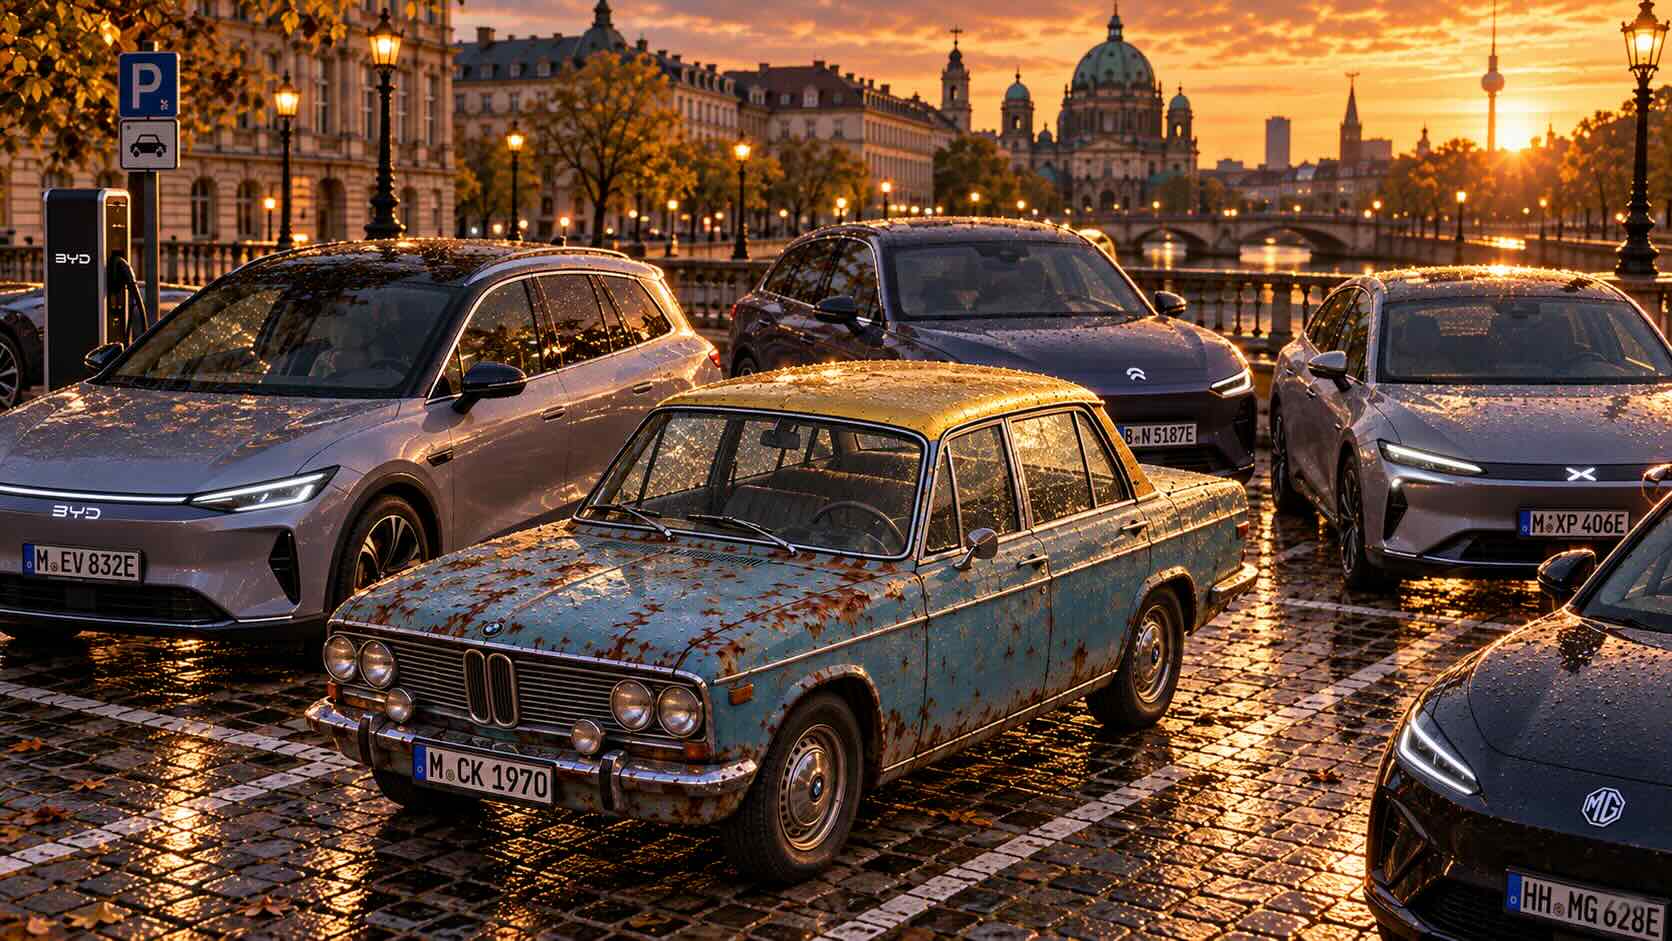
When Commission President Ursula von der Leyen gave her State of the Union speech, she couldn’t put enough emphasize on the thought: European industry is dying.
Mostly due to the insane amounts of cheap (and mainly Chinese) products dumped on the Single Market – good for those searching for cheap alternatives, but bad for the European manufacturers who (used to) produce high quality stuff.
The process is well-researched and documented: outsourcing production to places with lower labour costs might have seemed wise at first, lowering the costs. But it inevitably lead to jobs lost at home, factories closed – and vital knowledge transferred to Chinese companies.
Igniting a vicious downward spiral that can eventually lead to a serious dependence on China and the complete demise of European industry, one sector after the other.
Europe’s once prestigious car industry is the greatest example – how a complete industry can face struggles within less than a decade.
August 2026 data show that on a year-to-year basis, the European car market grew by 5.3 percent reaching 7.5 million new registrations in the EU.
The rise was primarily driven by increased demand for electric vehicles which is compensating for the steep drops in petrol and diesel car sales. While the latter dropped to a combined 29 percent market share, hybrid-electric vehicles became the most popular choice with 36.6 percent market share.
Unfortunately, intra-EU manufacturing is still roughly 3 million units below the 2019 (pre-pandemic) levels. Facing structural headwinds (high local/regional energy prices, expensive domestic production) – European carmakers are waging an increasingly unfair battle against low-cost Chinese automotive brands. Their footprint across the EU and UK is growing at an exponential pace.
For now, the car industry is still one of the main European industrial sectors. But the companies that once were real powerhouses of our economies, are now in survival mode.
In 2020, the automotive industry gave 13.8 million direct and indirect jobs in the EU (representing around 11 percent of the EU’s manufacturing employment) and added around 7 percent to the European GDP. The sector had one of the most ambitious Research & Development segments with around 30-32 percent of all European R&D contribution.
From the outside, it still doesn’t look that bad. Unfortunately, the state of the engine can be diagnosed only if one opens the hood.
The European car industry is not “dying” in terms of consumer demand, but it is undergoing a permanent, severe crisis.
During the last two years, the alarm bells started to ring.
Lot has been written about the state-of-the-art Chinese development, the fast innovation and never-seen car features – put in parallel with the slow and sleepy reaction of Europe.
The results of these opposing processes are now painfully visible. While regional sales have slowly grown by 5.3 percent, legacy European automakers are facing a “perfect storm”: overcapacity, expensive local manufacturing, and aggressive competition from BYD and other Chinese electric vehicle (EV) manufacturers. State-sponsored Chinese companies learned to manufacture great cars, with good smart and IT background and occasionally very innovative technologies. Their prices, (supported by governmental subsidies and overproduction), are way lower than the European manufacturers’ offers.
European car industry had its peak between 2018 and 2019, but then it collapsed during COVID. The pandemic was followed by years of stagnation.
Now, as consumers have started to recover and are ready to buy, they find that in the meantime, Chinese competitors arrived. They dictate new price tags – prices European production is not able to compete with.
In times when European consumers are more price-sensitive than ever (as they simultaneously need to weather several kinds of price shocks and huge inflation in every segment of their lives), Chinese brands are suddenly very attractive. No wonder they earn the most from the growing sales.
To put it shortly: for the first time in history, local sales do not help European brands – instead, they highlight their weakness stronger than ever.
European car factories are currently operating at a dismal 59 percent capacity utilization rate, well below the 80 percent threshold required for profitability. Analysts estimate that nearly a third of Europe’s 90 car plants are now financially unviable.
At the same time, Chinese EV brands manufacture vehicles at roughly 40 percent lower costs than legacy giants like VW or Renault. This cost benefit has allowed Chinese brands to fast-track their EU market share to over 11 percent during the last 4-5 years.
And it’s not just the lower production costs.
At first, it is difficult to understand that one of VW Groups biggest problems is that they are too small and do not cover the full spectrum of car production. But taking a look at a Chinese company like BYD is enough to see that it is completely vertically integrated. It owns its own lithium mines, manufactures its own microchips, and builds its own batteries (the most expensive part of an EV).
European brands must buy these components from third-party suppliers, drastically inflating costs. Not to mention that China refines over 70 percent of the world’s lithium and controls the vast majority of the global battery ecosystem.
Chinese state subsidies also tilt the balance in favour of those companies. Beijing poured around EUR200 billion in industrial subsidies into its EV sector between 2009 and 2024. This covered the initial high-risk R&D, allowing companies to build hyper-efficient mega-factories early on.
Of course, it’s not just Europe.
As the Chinese manufacturers’ domestic market is experiencing an oversupply (factories can build 40 million cars, but local demand is only around 20 million), they are flooding the rest of Asia. There, brands like Toyota, Honda, and South Korean brands suffered similar blows like their European counterparts. In countries like Thailand, Malaysia, and Indonesia, Chinese brands captured over 50 percent of the EV market. This represents a massive blow to Japanese automakers, who historically controlled over 80 percent of Southeast Asian roads but were slow to electrify.
These numbers lead only one direction: historic factory closures in Europe (and elsewhere).
In unprecedented moves, Volkswagen has been working on plans to shut down some of its German factories for the first time in its 87-year history, while Stellantis has targeted multiple factories for closure or downscaling. The ripple effect means that their parts suppliers (like Bosch, Continental, and ZF) will also have to scale down capacity, generating more layoffs.
More than 13 million European workers are in crisis, too.
Only one question remains. Is there enough strength left in Europe for take the steps it needs to protect itself? Let it be the adaptation required by the market or standing together and share the burden of repelling the Chinese wave together. The EU can help with supporting R&D, promoting and rewarding ‘loyalty’ to European brands and creating legislative barriers for Chinese products.
Otherwise, European giants like VW will likely disappear in the next decade.


